
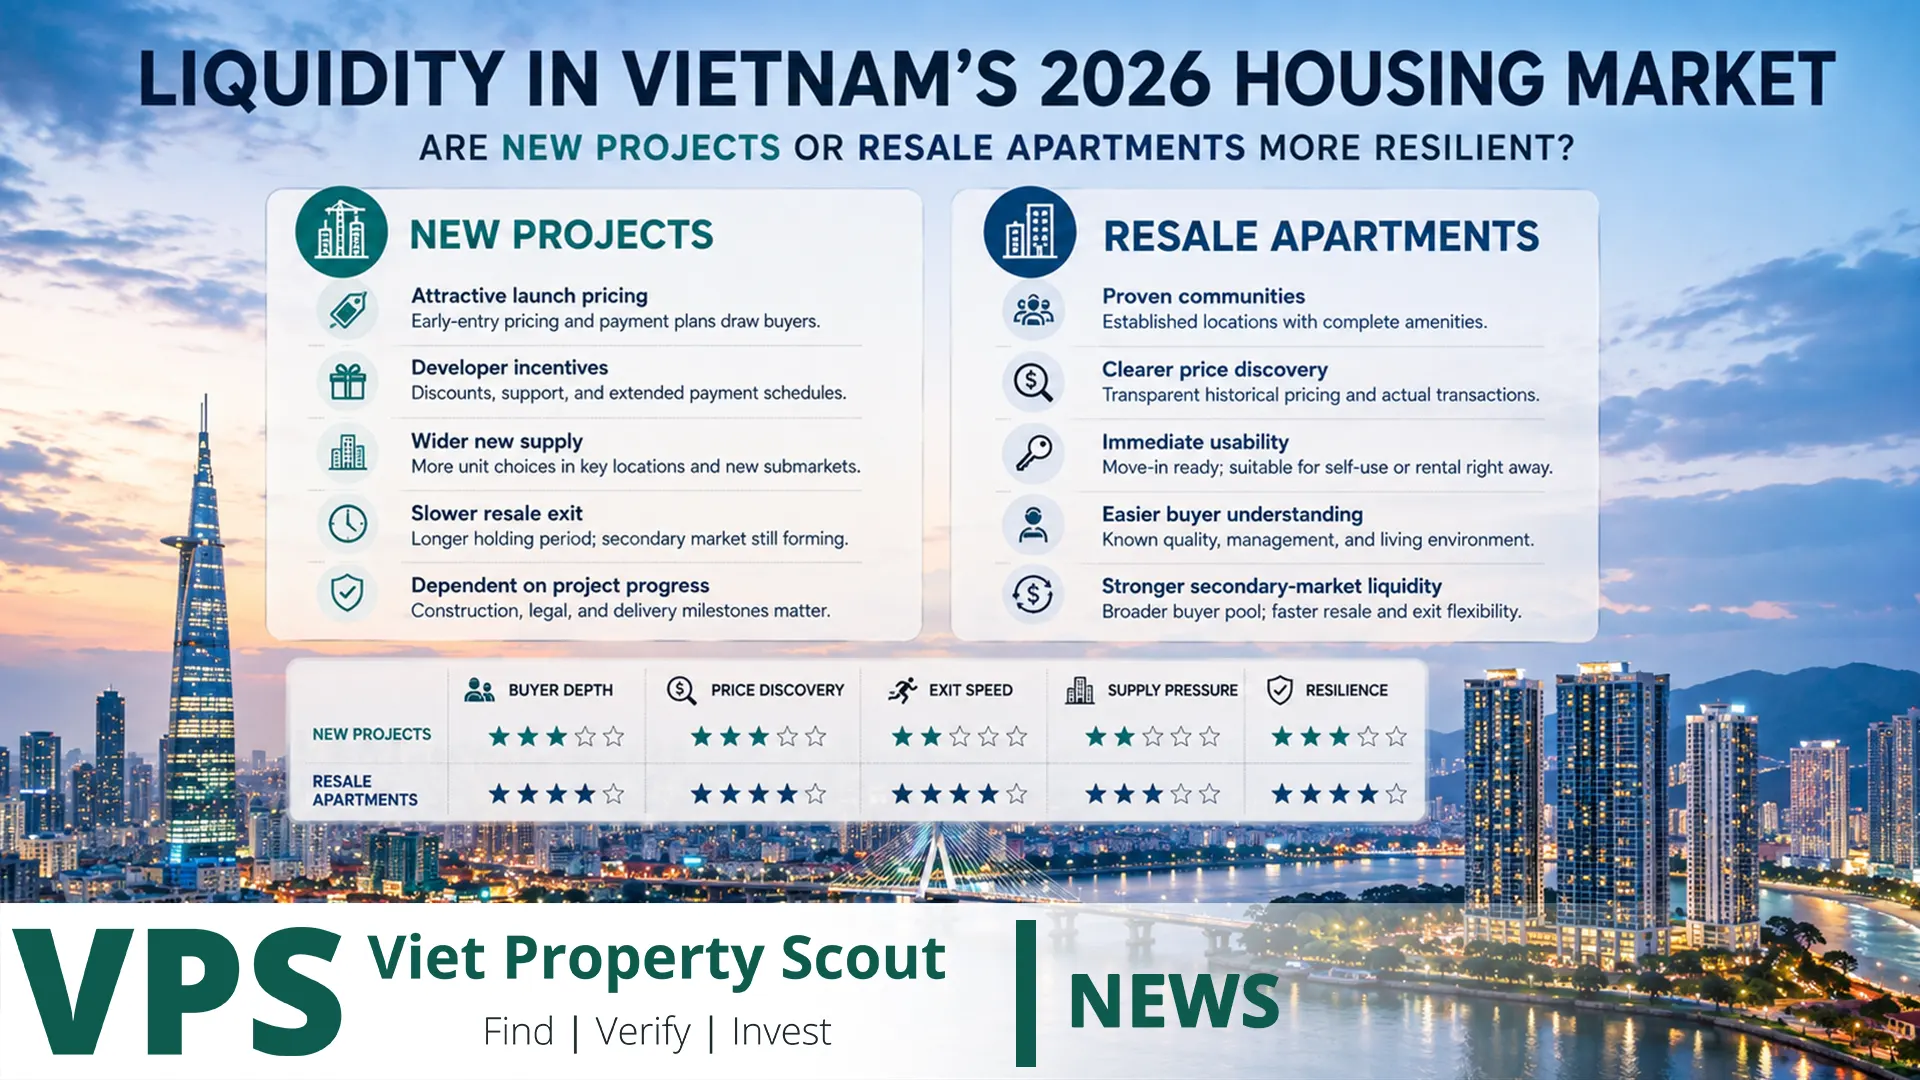
Liquidity has become one of the most important concepts in Vietnam's housing market in 2026. During a strong appreciation cycle, the investor's question is often, “How much can this property rise?” In a market shaped by higher interest rates, expanding supply and more selective buyers, a more important question is, “If I need to sell, how long will it take and what discount will I need to accept?” From that perspective, there is no simple rule that new projects are more liquid than resale apartments or vice versa. The critical distinction is between a developer's ability to generate first-sale velocity and an investor's ability to achieve a later resale exit.
What Does Property Liquidity Actually Mean?
Liquidity is not simply the existence of a buyer. A liquid residential asset can normally be sold within a reasonable period, at a price reasonably close to its observable market value, without a large distressed discount. Three variables therefore matter together: time to sell, discount required and size of the potential buyer pool.
A developer may sell hundreds of units rapidly through marketing, instalment schedules and subsidised financing. That does not prove that an investor buying one of those units will be able to resell it equally easily two years later. Conversely, an older completed apartment may attract less launch publicity but have a known rental market, established residents and a broad pool of end users.
The National Liquidity Picture in 2026
| Indicator | 2026 Position | Liquidity Signal |
|---|---|---|
| Successful Q2 transactions | 100,005, only 71.5% of Q1 | Market turnover has slowed materially |
| Reported inventory | About 39,284 units/plots across 25 of 34 reporting areas | Buyers have more competing choices |
| Property lending rates | Typically 12–14%, some floating rates 15–16% | Holding costs and buyer affordability are under pressure |
| Secondary market | Modest downward adjustments across apartments, villas and land | Motivated sellers have less pricing power |
| New supply pipeline | Strong expansion in newly approved housing projects | Future competition for buyers is increasing |
Three Different Markets Must Be Separated
Liquidity analysis becomes much clearer when housing is divided into three categories. The first is a direct primary purchase from a developer in a new project. The second is a resale or contract transfer for an apartment that remains under construction. The third is a completed resale apartment in an occupied building. These three assets can behave very differently under stress.
1. New Project: Strong Launch Liquidity Does Not Guarantee Strong Exit Liquidity
New developments have obvious advantages. Developers fund major advertising campaigns, mobilise extensive agency networks, offer staged payment schedules and sometimes subsidise interest rates. As a result, a project can appear extremely liquid during its launch period.
But that liquidity belongs primarily to the developer. If an investor later wants to sell while the developer still has unsold inventory, the investor may be competing directly with the project itself. The developer can offer payment incentives, discounts, furniture packages or interest support that an individual seller cannot replicate. A project can therefore have excellent “sales-channel liquidity” but poor investor resale liquidity.
2. Resale While Under Construction: The Most Finance-Sensitive Category
This category is particularly vulnerable when interest rates rise. An investor may have entered with a relatively small initial payment and later face much larger instalments or the expiry of a developer-supported loan period. If the investor does not want to commit additional capital, selling before handover becomes the preferred exit.
If many buyers in the same project reach that point together, multiple nearly identical units appear for sale. Price becomes the primary competitive tool. This dynamic has become more visible in Hanoi, where higher financing costs and the expiry of principal grace periods for owners of under-construction properties have contributed to lower asking prices in order to stimulate transactions.
3. Completed Resale Apartment: Less Marketing, More Measurable Reality
A completed apartment has one major advantage: the buyer can inspect what actually exists. Building management, elevators, parking, noise, retail, occupancy, resident profile, construction quality and maintenance standards are observable rather than projected.
If the apartment is already rented, income can be calculated from real contracts rather than developer forecasts. An end user can also move in immediately. These characteristics broaden the buyer pool and can make a well-located completed apartment in a functioning community one of the more resilient residential assets during a liquidity slowdown.
Why a Resale Apartment Can Be More Resilient
- No construction-completion risk.
- Actual building quality can be inspected.
- Real achieved rents can be verified.
- Occupancy and daily services are already proven.
- Transaction history in the building or neighbourhood can be compared.
- End users can move in immediately, expanding the buyer base beyond investors.
That does not mean every resale apartment is liquid. Poor management, ageing infrastructure, high service charges, legal problems, weak parking, undesirable layouts or a large number of competing listings can materially reduce resaleability.
Why a New Project Can Still Be More Resilient in Certain Markets
A new development can outperform when several conditions exist simultaneously: a strong developer, clear legal eligibility, genuine local supply scarcity and a primary price that remains competitive with completed alternatives. Flexible payment plans can also attract buyers who cannot immediately fund the full purchase price of a completed property.
In a market such as established HCMC, where only 850 new condominium units were launched in Q2 2026, selected legally sound developments can benefit from genuine scarcity of new stock. But that advantage disappears if the developer asks a substantial premium over comparable completed apartments.
Hanoi: The Clearest Example of Primary–Secondary Liquidity Divergence
More than 5,800 condominium units were sold in Hanoi in Q2 2026, but this represented only around 68% of new supply launched during the quarter. That was far below the 2024–2025 period, when absorption frequently exceeded 90%. The secondary market also recorded its first downward price adjustment since late 2022.
This environment illustrates an important point. Developers can continue launching new units at relatively high headline prices while individual owners in the secondary market begin accepting lower prices to obtain liquidity. An investor who watches only primary list prices can miss the level at which real transactions are actually clearing.
HCMC: Restricted Primary Supply Gives Selected New Projects Some Protection
HCMC's Q2 2026 new condominium supply fell to only 850 units. The established core therefore does not currently face a Hanoi-style flood of apartments. Legally sound new projects in genuinely supply-constrained locations can enjoy some liquidity support from scarcity.
Entry price remains decisive. A new apartment in Thu Thiem or Thảo Điền may have an excellent location, but if it is materially more expensive than a completed and already-rented comparable property, the completed unit may ultimately be easier to resell because the ticket size is lower and the rental economics are visible.
New Project vs Completed Resale: Direct Comparison
| Factor | New Project | Completed Resale Apartment |
|---|---|---|
| Marketing | Very strong developer and agency support | Dependent on owner and broker |
| Payment structure | Instalments and interest support may be available | Often requires more immediate capital or financing |
| Actual quality | May not be fully observable before completion | Can be inspected directly |
| Rental evidence | Forecast | Actual achieved rents can be checked |
| Seller competition | Investor may compete with the developer | Competition mainly from other owners |
| Completion risk | Exists before handover | Absent for completed property |
| Buyer pool | Investors and buyers willing to wait | Investors plus immediate owner-occupiers |
| Liquidity measurement | Difficult before handover | Easier using real transaction history |
The Viet Property Scout Residential Liquidity Ladder
Assuming comparable location and general quality, a practical 2026 resilience ranking can look roughly like this:
- A completed, legally clean apartment in an occupied community at a realistic price.
- A legally sound new project from a strong developer in a genuinely supply-constrained location at competitive pricing.
- A completed apartment that is overpriced or in a weaker building.
- An under-construction resale with many similar competing sellers.
- An overpriced new project whose investment case depends primarily on future capital appreciation.
Interest Rates Change Which Asset Wins
At mortgage costs of 12–14%, assets requiring substantial leverage become more liquidity-sensitive. A new project may initially look affordable because of developer interest support or delayed principal repayment, but monthly obligations can rise sharply after those incentives expire. Some investors then become motivated sellers.
A completed apartment producing actual rent can offset part of the financing cost and may therefore remain more resilient, provided the purchase price itself is not excessive.
Foreign Buyers Have an Additional Liquidity Test
For a foreign investor, liquidity is not solely about market price. The project must be eligible for foreign ownership and the foreign ownership quota for the exact apartment must be checked. Under current rules, foreign organisations and individuals can generally own up to 30% of the residential apartments in an eligible apartment building.
The potential buyer pool at exit also matters. A unit that is difficult to transfer to another eligible foreign buyer, or has unclear ownership documentation, can be less liquid despite an excellent location.
How to Test Liquidity Before Buying
| Question | Strong Signal | Risk Signal |
|---|---|---|
| How many similar units are for sale? | Limited competing inventory | Dozens of nearly identical listings |
| Who is the next buyer? | Both end users and investors | Only another investor |
| Are there real rental records? | Clear achieved rent data | Only marketing forecasts |
| How large is the premium over resale stock? | Small or fundamentally justified | Large with no clear justification |
| Will I compete with the developer? | Little developer inventory remains | Large unsold developer stock |
| Can someone occupy the property immediately? | Yes | Years of waiting remain |
The Viet Property Scout Method
- Find: Do not simply search for the most heavily marketed project. Find the asset with the broadest plausible future buyer pool.
- Verify: Check legal status, competing inventory, achieved rent, real transaction history and foreign quota where relevant.
- Invest: Calculate the exit before entering. If you had to sell within twelve months, how much discount would realistically be required?
Verdict: Which Is More Resilient in 2026?
New developments in Vietnam generally have an advantage in first-sale liquidity because the developer controls marketing, payment structures and distribution. A good completed resale apartment, however, often has an advantage in true exit liquidity because immediate use, actual rent, established community quality and comparable transaction evidence are already visible.
For a conservative investor who places significant value on the ability to exit, a completed apartment in a legally clean, occupied project at a realistic price will therefore often be more resilient than an under-construction unit. A new project can be superior when genuine scarcity, strong developer execution, clear legal status and disciplined pricing all exist together.
Conclusion
The central liquidity question in Vietnam's 2026 housing market is not simply “new or resale?” It is “Who will be the next buyer, and why will that buyer choose this asset?” A new project supported only by a future appreciation story can become difficult to exit after the launch campaign ends. A good resale apartment can remain liquid because it has real users and measurable income.
The strongest defence for 2026–2027 is therefore to buy an asset that still makes economic sense without relying on continued broad market appreciation. Clear legal status, defensible pricing, measurable rent, a functioning community and a broad buyer base turn liquidity from a marketing promise into a characteristic of the property itself.